
Remortgage to Buy Another Property: How UK Lenders Decide in 2026
See how to remortgage to buy another property, and check how two lenders will each assess the plan.
Quick Answer
You can remortgage your home to release equity and use the money to buy another property, most often as the deposit. The lender on your home must accept the purpose and be satisfied you can afford the larger mortgage. The lender on the new property assesses that purchase separately.
Two sets of criteria therefore apply. The first lender looks at your income and all your commitments, including the new mortgage. The second looks at the new property, and at the rent if it is a buy-to-let.
The plan increases the debt secured on your home, so it carries more risk than buying from savings. This guide covers the ways to release equity, what each lender checks, how much you can raise and the alternatives.
What do you need first?
Tap one to start your check. No credit search.
Reviewed by Ben Stephenson, FCA-authorised mortgage adviser (FRN 496907) · 25+ years' experience · 4.9★ on Google. Updated: 18 November 2026.
Who Is This Guide For
Best for homeowners with equity who want to buy a rental property, a second home or a home for a family member, and for those moving who want to keep their current home and let it.
Key Points
Equity can fund the deposit on another property
Two lenders assess the plan separately
More debt on your home means more risk
Table of Contents

How remortgaging to buy another property works
The idea is simple. Your home is worth more than you owe on it, and that difference is equity. A lender may let you borrow against part of it. You take the money as a lump sum and put it towards another purchase.
Most people use the money as a deposit and take a second mortgage on the new property. A homeowner might raise £60,000 against their home and use it as a 25% deposit on a £240,000 rental flat, with a buy-to-let mortgage for the rest. Some raise enough to buy outright, though that needs a great deal of equity.
Three routes release the money. A remortgage replaces your current mortgage with a larger one from a new lender. A further advance is extra borrowing from the lender you already have. A second charge is a separate loan secured behind your existing mortgage.
Whichever you choose, the result is the same. You owe more on your home than before, and you have a second property with its own mortgage. Both debts have to be serviced whatever happens to rents, rates or your income.
Our pillar guide to remortgaging covers the process, and our guide to releasing equity explains the options in more detail.

What the money can be used for
Lenders ask what the money is for, and the answer affects which of them will help. Buying property is a widely accepted reason for raising capital, but lenders draw their own lines.
What you are buying | What it means for the lending |
|---|---|
A buy-to-let | The most common purpose; the new mortgage is assessed on the rent |
A second home | A second residential mortgage, tested on your income |
A home for a family member | Lenders differ; some treat it as buy-to-let, some as residential |
Your next home, keeping this one to let | Known as let-to-buy; needs consent or a buy-to-let mortgage on the old home |
Property abroad | Fewer lenders accept it as a purpose |
Buy-to-let is the purpose lenders see most. The rental property is expected to pay its own way, which limits the extra strain on your household budget. Our pillar guide to buy-to-let mortgages explains how those loans are assessed.
A second home is harder on affordability. With no rent coming in, you are paying two residential mortgages from one income, and lenders test that carefully. A holiday home that you also let to guests is a different product again, covered in our guide to holiday let mortgages.
Keeping your current home and letting it when you move is a variation. GOV.UK's guidance for landlords says you must get permission from your mortgage lender before renting out a property. In practice that means consent to let from your lender, or a new buy-to-let mortgage on the old home.
Buying an additional property also has tax consequences. Those are outside mortgage advice, so speak to an accountant or solicitor before you commit.
What the lender on your home checks
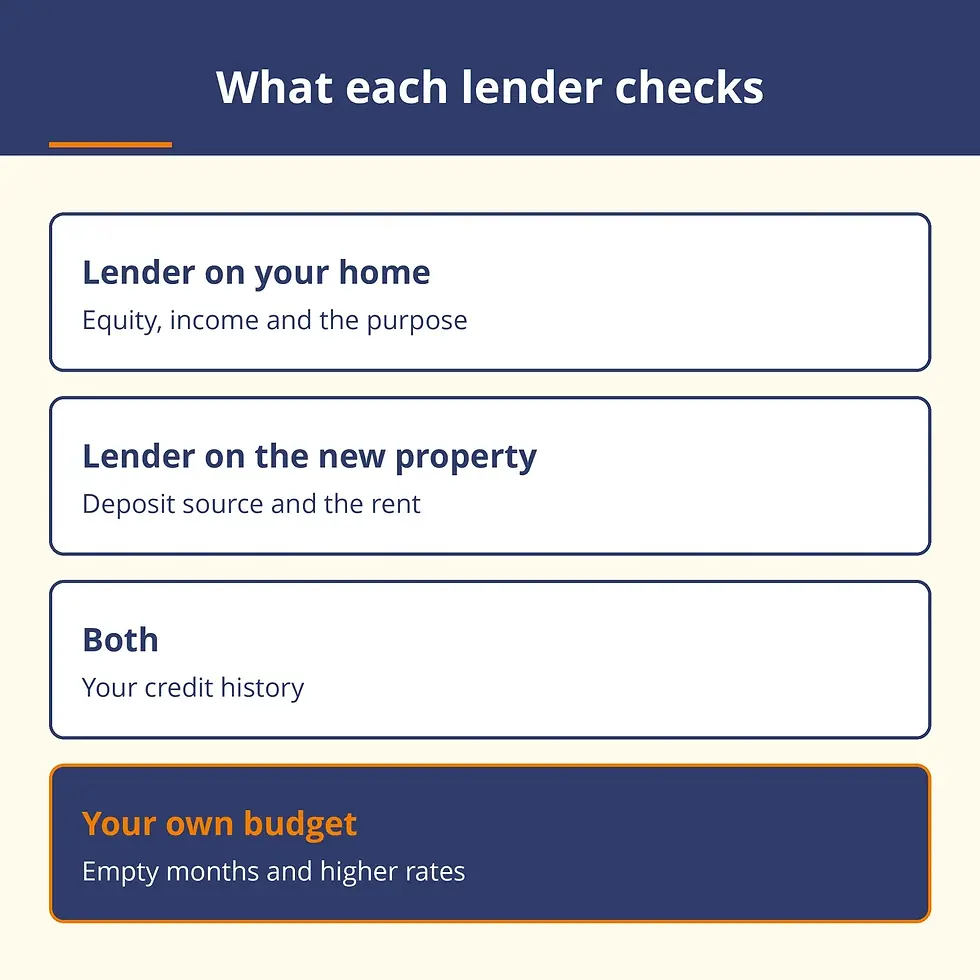
The lender releasing the equity treats it as ordinary capital raising with a stated purpose. Three things decide the answer: how much equity you have, whether you can afford the larger loan, and whether the lender accepts the purpose.
Affordability is tested on the new, larger mortgage. The lender also counts the commitment you are about to take on. A new buy-to-let mortgage is usually treated as self-funding if the rent covers it. A second residential mortgage is counted in full as an outgoing.
Lenders differ on how much they want to know about the purchase. Some are content with a statement that the money is a deposit for a buy-to-let. Others want evidence that a property has been found, such as a memorandum of sale, before they release funds.
How many UK residential lenders may consider a remortgage to buy a buy-to-let in 2026?
At least 3 of the 44 UK residential lenders whose published criteria Manor Mortgages Direct tracks may consider remortgaging to fund a buy-to-let purchase, as at November 2026. The other 41 publish no position on this purpose and are not counted.
Source: Manor Mortgages Direct criteria tracker, 44 UK residential lenders, checked November 2026. The count covers only lenders that publish a rule naming this purpose. Many lenders accept property purchase as a reason for raising capital without publishing a specific rule, so the true number is likely to be higher. Counts describe the lenders tracked, not the whole market.
The published rules that do exist show the pattern. Two of the three cap this kind of borrowing at 80% of the home's value. One of them may consider it only once the buy-to-let has been found.
Your payment record counts as well. A lender asked to increase a mortgage looks at how the existing one has been run. Missed payments in the last year or two make extra borrowing much harder to arrange.
Let-to-buy in more detail
Let-to-buy is the usual name for keeping your current home as a rental and buying a new one to live in. It involves two transactions at once. The old home moves onto a buy-to-let mortgage, often releasing equity, and that equity becomes the deposit on the new home.
Both lenders need to see the whole picture. The buy-to-let lender tests the rent on your old home. The residential lender on the new home counts the rental mortgage as covered by that rent, provided it passes the test. Some lenders offer both halves together, which keeps the timing simple.
What the lender on the new property checks
The second lender has its own questions, and the first is where the deposit came from. Money raised against another property is an accepted source with most lenders, provided it is disclosed. They will ask for the mortgage offer or completion statement showing the funds.
For a buy-to-let, the main test is the rent. The expected rent must cover the mortgage interest, calculated at a notional rate, by a set margin. A deposit of a quarter of the price is a common minimum. The lender also checks that you can cover the mortgage when the property is empty.
Many buy-to-let lenders set a minimum income, and some want you to own your home already, which you do. First-time landlords are accepted by a good number of lenders, though the choice is narrower than for someone with experience.
For a second home, the lender runs a full residential affordability check with both mortgages included. Deposits are typically larger than on a main home, and some lenders will not offer their highest loan to value on a second property.
Timing links the two applications. The equity has to be released before the purchase completes, so the remortgage normally runs a few weeks ahead. Offers have expiry dates, and a delay on one side can put pressure on the other.
Ownership structure is worth settling early. Some buyers hold a rental property jointly, some in one name and some through a limited company. Each choice affects which lenders are available and how the purchase is assessed, and it has legal and tax consequences that an accountant or solicitor should explain.
How much you can raise
The limit comes from two directions. The lender caps the total loan as a share of your home's value, and it caps it again by what you can afford. The lower figure applies.
Take a home worth £400,000 with £180,000 owed. A lender prepared to go to 80% would lend up to £320,000 in total, which would release as much as £140,000. Whether you could borrow that much depends on your income and outgoings.
Loan to value limits for capital raising are often lower than for a purchase. Some lenders reduce their maximum when money is being taken out for any purpose other than home improvements. Others treat all purposes alike. The difference between lenders can be tens of thousands of pounds.
The rate on the whole mortgage can change too. Borrowing more may move you into a higher loan to value band, which raises the rate on every pound, not only the new money. That cost belongs in the sums for the new property.
Fees add to the amount you need. Valuation, legal and arrangement fees apply on both sides, and the purchase has its own costs. Raising slightly more than the deposit avoids a shortfall at completion.
If you are tied into a fixed rate, check the early repayment charge. Remortgaging before the deal ends may cost more than the alternatives. Our guide to a further advance or a remortgage compares the two.
A typical case: one deposit, two mortgages
This is an illustrative composite, not a real client. A couple own a home worth £420,000 with £150,000 left on the mortgage. Their fixed rate ends in three months. They want to buy a £200,000 flat to let.
They remortgage to £205,000, which is 49% loan to value, releasing £55,000. Of that, £50,000 is the 25% deposit and the rest covers costs. Their lender asks what the money is for and accepts a buy-to-let deposit as the purpose.
A buy-to-let lender then offers £150,000 on the flat, tested against an expected rent of £950 a month. The couple now have two mortgages totalling £355,000 where they had one of £150,000. The rent covers the flat's mortgage, but the extra £55,000 on their home is paid from their own income.
Further advance and second charge
A remortgage is not always the best way to release equity. If your current rate is low and has years to run, replacing the whole mortgage could be expensive.
A further advance leaves the existing mortgage alone. Your lender adds a second, smaller loan on a rate available today. There is no early repayment charge and often no legal work. The drawback is that you are limited to one lender's criteria and its view of the purpose.
A second charge comes from a different lender and sits behind your mortgage. It costs more than a first mortgage, but it leaves a good rate untouched. Second charge lenders are often flexible about purpose and about income. Our guide to remortgage or second charge sets out when each fits.
Short-term finance has a place when timing is the problem. If you have found a property and cannot wait for a remortgage, a bridging loan secured on your home can provide the deposit quickly. It is expensive and needs a clear way out, usually the remortgage itself.
What do you need first?
Tap one to start your check. No credit search.
Our guide to raising money on your mortgage compares all of these routes side by side.
The risks to weigh
Borrowing against your home to invest is a geared bet. If the new property rises in value and lets well, the gain is yours. If it falls, or stands empty, the debt on your home is unchanged.
Your home may be repossessed if you do not keep up repayments on your mortgage. That warning applies with more force when the mortgage has been increased to fund another purchase, because the extra borrowing is secured on the place you live.
Rent can stop. Empty months, repairs and tenants who fall behind all have to be covered from your own income. Lenders test for this, but their test is a minimum and your own budget should be more cautious.
Rates move. Both mortgages will come up for renewal, possibly at higher rates than today. A plan that works only at current rates is a fragile one, so test the sums with rates a couple of points higher.
Selling is slower than borrowing. Property takes months to sell and costs money to dispose of. If you might need the equity back at short notice, it should not be tied up in a second property.
Your circumstances can change as well. A period out of work, illness or a growing family all reduce what you can spare. Keeping a reserve equal to several months of payments on both mortgages gives you time to react.
What we see in these cases in 2026
Raising money to buy another property is a small share of our capital-raising work. Of the 50 capital-raising cases on our records to November 2026, eight involved buying, or putting a deposit on, another property. Debt consolidation and home improvements were both more common.
Eight cases is too few to generalise from. What they have in common is that the purchase side needed as much attention as the remortgage, because two lenders had to be satisfied in the right order.
The published criteria are thin on this purpose. Few of the lenders we track publish a specific rule on raising money for a buy-to-let, and those that do set a loan to value cap. Most lenders decide case by case, which makes it worth checking the purpose before an application goes in.
The cases that run smoothly start with the numbers for both properties on one page: what can be released, what the new mortgage will be, what the rent covers and what the household pays from its own pocket.
How to apply
A little preparation keeps the two applications in step.
Value your home realistically. Use recent sales nearby, not asking prices.
Check your current mortgage. The balance, the rate, the end date and any early repayment charge.
Decide the purpose. Buy-to-let, second home, family or let-to-buy.
Work out both sets of payments. The larger mortgage on your home and the new one.
Research the rent. For a buy-to-let, what similar properties let for.
Check criteria before applying. Match your equity, income and plans to lender criteria first.
From there, an agreement in principle on both mortgages confirms the plan before you make an offer on the new property.
FAQs
Can you remortgage to buy another property?
Yes. You can release equity from your home and use it towards another purchase, usually as the deposit. Your lender must accept the purpose and be satisfied you can afford the larger mortgage.
How much equity can you release to buy a second property?
It depends on your home's value, what you owe and your income. Lenders cap the total loan as a share of the value, often lower for capital raising than for a purchase, and apply an affordability check.
Do you need two mortgages?
Usually, yes. The larger mortgage on your home provides the deposit, and a separate mortgage on the new property funds the rest. Each lender assesses its own loan.
Can you use equity as a deposit for a buy-to-let?
Yes, with most buy-to-let lenders, provided the source is disclosed. The new mortgage is then assessed mainly on the expected rent.
Is it better to remortgage or take a further advance?
A remortgage suits you when your deal is ending. A further advance or second charge avoids early repayment charges and leaves your current rate in place, though the new borrowing may cost more.
Summary
Remortgaging to buy another property means two lenders and two sets of criteria: one releasing equity from your home, one lending on the purchase. How much you can raise depends on your equity, your income and the purpose. The plan adds debt to your home, so test it against empty months and higher rates. If you would like your plans matched to lender criteria before you apply, the check takes a few minutes and involves no credit search.
Reviewed by Ben Stephenson, FCA-authorised mortgage adviser, CeMAP-qualified.
Manor Mortgages Direct is FCA authorised, FRN 496907, has traded for 25 years, is highly positively reviewed, 4.9 rated on Google, and has helped thousands secure the right mortgage. Bristol-based mortgage brokers, assisting clients nationwide.
Sources
GOV.UK, Renting out your property: landlord responsibilities, accessed 17 November 2026
Cite this page: Manor Mortgages Direct, "Remortgage to Buy Another Property: How UK Lenders Decide in 2026", checked November 2026, manormortgagesdirect.com/remortgage-to-buy-property
Related Guides